My Deadbeat Uncle
This post was written in April with some additions before publication.
I have a deadbeat uncle. The entire family knows him, but we don’t like to talk about him. He’s terrible at managing his money, picks fights, and ticks a lot of people off. Half the family hates him, though which half changes continuously.
He has a lot of flaws, but deep down I like him and want to help him. So I send him money every month. When I first started, he would always ask for more at the end of the year. It ticked me off, but eventually I started sending him more each month instead. Eventually at the end of the year he stopped asking for more and would occasionally give a tiny bit back. It was only a fraction of what I gave him, but it was nice to get a little back.
I am now so used to sending him money that it’s a part of our unofficial budget (we don’t really keep a traditional budget).
When I am paid back, it’s like receiving a bonus check from work. We invest or save the money when we do receive it, and grumble a little when we don’t. I know some of the money we give him is wasted, but he puts some of it to great use, so we don’t really complain or think too much about it anymore.
Not a Real Uncle
Yes, my Uncle Sam is an interesting guy. For several years we have to paid him a little extra through paycheck deductions in order to receive a refund at tax time.
This use to be widely criticized as giving Uncle Sam an interest-free loan. Most financial advisors recommended adding more to your paycheck and then paying more taxes at tax time. I always considered that bad advice, but especially hated it the first time as a resident I owed a couple grand at tax time.
Sign up to receive email notifications of posts. Follow me on X, Facebook, or Instagram for entertainment and updates of new posts. Feel free to email me with comments, questions, or to ask about site sponsorship or public speaking.
Underpaying taxes works if you have enough cash flow to just pay the tax bill at the end of the year, or if save some each month just to have money to pay the taxes.
Most people don’t have that much cash flow – many households in the United States can’t cover a $500 emergency, let alone a much larger tax bill. While our family has better cash flow and emergency reserves than most, we still aim for a refund each year.
While we could attempt to adjust our withholdings to get close to neutral, that requires having a good idea of income and deductions. If your income fluctuates or your deductions are going to have big changes, it’s a guessing game that could change by a few thousand dollars either way.
So we try to err on the side of a refund, because we’d rather just not have to consume a month’s expenditures on taxes, and we consider emergency savings to be for actual emergencies, not something that can be anticipated.
Human behavior also rewards the refund. Give me an extra $100/month direct deposit and it’s absorbed into our discretionary spending. Give me a $1,200 check and we won’t be blowing it at Whole Foods (not that we go there). Instead it is put towards some savings or investment account.
For the 2015 tax year we received a combined federal/state refund of about $2,000, a pleasant amount that went straight into a Backdoor Roth IRA. The 2016 tax year was a different story, as two major events led to a large change in our tax burden.
Kids Just Keep Comin’
We had another child, and because of that child, we needed a larger house. Three boys in one small bedroom wasn’t going to work, especially when our then 2-year old basically had to be chained to the radiator to keep him from roaming the house after hours (no children were harmed in the making of this blog post; do not call social services).
I knew this would change our taxes, but we didn’t adjust our withholdings. I was uncertain enough about changes to our adjusted gross income that it was a bit of a guessing game. I was also just distracted.
When we calculated our 2016 taxes, our refund went up substantially. I would say it was a shock, but it wasn’t. The extra exemption from a third kid and increased itemized deductions from higher mortgage interest and real estate taxes were expected to decrease our taxes. Our income was basically flat (really a little lower because of maternity leave).
A refund this large give me pause. We don’t live a lavish lifestyle, but because we’ve set high savings goals (compared to most of the U.S.) and have multiple kids (2 in daycare), our monthly disposable income is modest.
A few hundred extra dollars goes a long way when you are frugal – the last shirt I bought cost me $1.50 at a thrift store. My wife prefers clothes that didn’t have previous owners, but she’s not a spendthrift.
So for the first time in several years, I’ve adjusted my withholdings to put a bit more back into my paycheck.
Wonderful blogger White Coat Investor always says not to sweat the little things if you are doing the big things right. I think we’re doing the big things right, but I admit that somewhere along the way I became paranoid about lifestyle creep.
I splurge, but it generally involves experiences such as major sporting events or travel. I told my wife last year when planning our 10-year anniversary trip I was going to spend an ungodly sum of money to see Hamilton on Broadway. Yet regular trips to Starbucks raise my hackles.
I recognize that may be a bit self-serving and maybe even hypocritical or short-sided, so I’m trying to adjust, but my fundamental view of where money should be spent is difficult to change.
We’re the 1%
What my wife and I both do is every so often remind ourselves that we are in better shape than 99% of the world. Uncle Sam may be a deadbeat, but he’s given me opportunities that billions of other human beings around the world will never have.
Many people in this country are deciding between rent and groceries, not Hamilton vs. Starbucks, which as I think about it, makes this entire discussion seem a bit less important.
Congress has announced plans for a healthcare bill that will hurt millions of people in this country, a good proportion of which are children. I haven’t spent much time on politics in this blog, but Uncle Sam has never felt more like a deadbeat to me than he does right now.
I’m willing to pay higher taxes if it will help children and the disabled have access to healthcare. Uncle Sam (and Uncle Donald) apparently don’t want my money. They want me to buy more Starbucks from baristas that can’t afford the products they serve (and can’t afford the ER bill from my hospital if they are in a car accident while driving home).
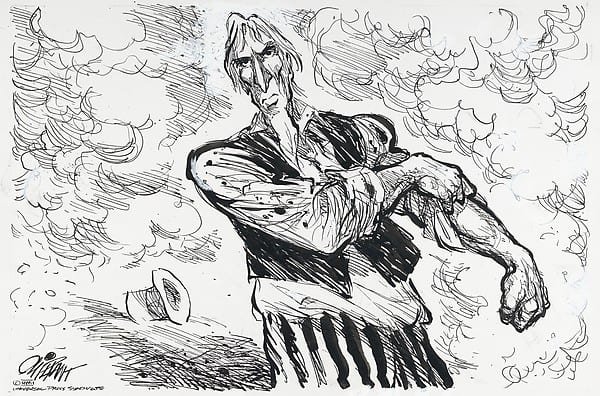
I’ve had gripes with our government through every administration, including when the people I voted for won. I like to think of Uncle Sam like this picture — rolling up his sleeves and getting hands dirty to help people, even when it’s not popular. Now he just seems dirty.
What are your thoughts on Uncle Sam and taxes? Do you “count” on a refund each year? Have you in into lifestyle creep? Are you happy with how your tax money is spent?

A h Uncle Sam. We always get a refund but this year I increased my deductions and am hoping to come out at a 0 or maybe a small return. My pay check take home amount has increased so that is nice, but time will tell if it is the right decision.
Still waiting on some tax reform from our current administration, but I guess health care and deportations are higher on the agenda.
I’m a big fan of forced savings. Aiming for a small refund is also another way to ensure you don’t overspend and can live on less. The refund I received this year was a bit much, but I like it when we get 1-2k back.
Also I wouldn’t say health care is high on the agenda — they are rushing it through as fast as possible and don’t care what the public thinks.
I have had years with refunds and years where I have had to pay. I tend to prefer to pay a little then get a bunch back.
Medical is such a big topic and really there is just so much waste. But honestly, I feel I already do pay a lot in taxes and then give to our church and some other charitable causes. I think waste should be cut and some other measures put in place before our taxes raised anymore.
cd :O)
Sure, waste can always be cut. However it isn’t wasteful to provide healthcare to people. The new health care bill is lowering taxes for the rich. If they just kept it the same and did a better job budgeting and working towards more efficient use of the health care system then they could provide care for most/all Americans via some mix of methods.
Donating to a church and other places is great (we do the same), but there’s no private organization in this country that can do this for large groups of people.
Any refund I get I just apply it to my next quarterly estimate. My income jumps around
I owed much more this year (typically I owe $100-200 & that’s tough to adjust for) but my side hustle, teaching yoga, brought in more money than I expected. I don’t get paid for classes I don’t teach (weather cancellation or no show to class), and started the year without a regular class. I expected to substitute a class once a month maybe. Then I was offered a weekly class, plus substituting some classes.
In addition to my regular class, this year started with a once a month workshop for 3 months, which became 6 months and may be scheduled for another 3 this fall. 🙂
I am looking into eligibility for a solo 401k (or similar ) for tax savings, because I can contribute as employer and employee vs maxing my 9-5 401k, saving my yoga earnings, paying taxes due (unemployment etc) and treating anything left as a refund. I’ll see how it all goes.
Having a large tax bill is painful, but the good news is your business sounds as if it is doing very well and generating more income than expected. Congrats — a good problem to have!